-
WELCOME to Uncle Alvin’s Blog
BLOG POST 1 — Ask Uncle Alvin About Uncle Warren Buffett’s Unique Perspective on Investing
Nieces and nephews may ask Uncle Alvin, what is the best thing that investors can do? One of the best investors in the world, Uncle Warren, says the best thing investors can do is to use 90% of their money allocated to investments to buy a very low cost S&P 500 index fund.

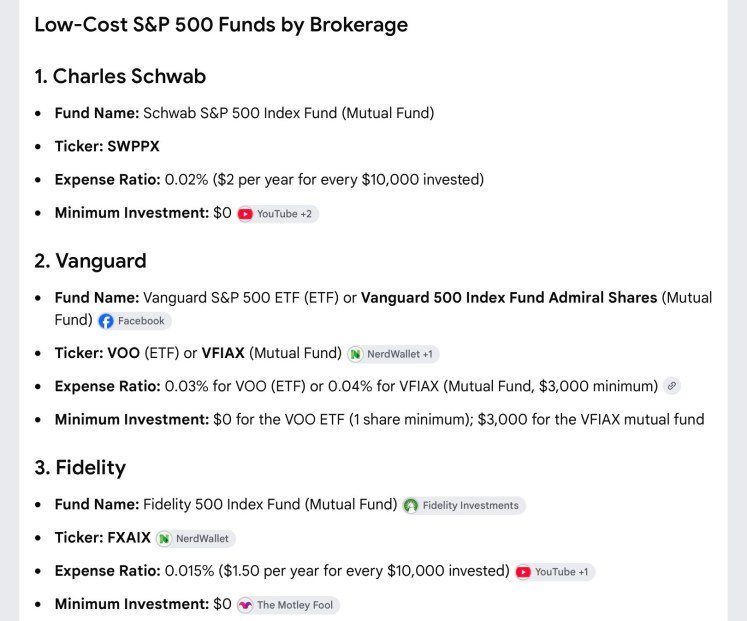
So Uncle Alvin says the best and easiest thing that nieces and nephews can do to invest is to just follow Uncle Warren’s expert investment advice — buy low cost stock index funds with expense ratios less than 0.05% like SWPPX, VFIAX or FXAIX.
BLOG POST 2 — Ask Uncle Alvin About Uncle Jack Bogle’s Unique Perspective On The Tyranny of Compounding Costs
Nieces and nephews may also ask Uncle Alvin, what is the worst thing that investors can do? One of the worst things investors can do is use financial intermediaries and high cost stock funds because the fees and costs can eventually take away 75% of the investment gains from unsuspecting investors.
Uncle Jack Bogle, founder of the Vanguard Group and an investment expert who introduced the first low cost stock index fund to investors, explains the disadvantages of high cost stock funds and the advantages of low cost stock index funds.
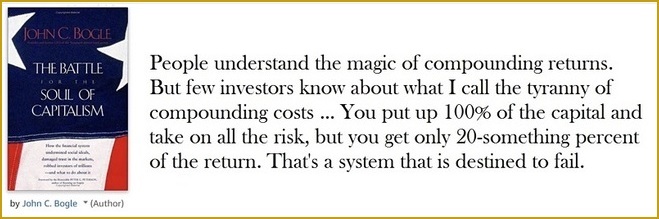
In his book The Battle for the Soul of Capitalism, Uncle Bogle explains that a system that involves financial intermediaries such as investment, wealth or advisory management firms and high cost stock funds takes away roughly 75% of the market’s return because of the tyranny of compounding costs and leaves investors with only about 25% of the market’s gains. Therefore, the system is designed to benefit financial intermediaries and fail investors.
Many investors ignore the fees and hidden costs charged by investment managers and high cost stock funds because:
1) the total annual fees and expenses of 2% or higher — for example, a 1% management fee for the manager and a 1% expense ratio for the funds — might not seem like a big deal and may even seem too “small” to ever worry about.
2) the fees and expenses are never itemized but are instead buried in the fine print and silently taken out without any bills or invoices or further notice to investors.
Unfortunately, as time goes by, the fees that once seemed too small to worry about, eventually compound to such a large amount over an investment lifetime that the fees of high cost stock funds end up taking more than 75% of the market’s return.
This means that high cost stock funds become toxic assets over time because unwary investors don’t realize much of the return has been taken away by the tyranny of compounding costs until it’s too late, after too many years have passed.
For example, after decades of investing, if the return from the stock market is $1 million dollars, a high cost mutual fund takes away as much as $750,000 dollars over that time and leaves investors with only $250,000, compared to a low cost stock index fund with an expense ratio under 0.05% that would leave investors with nearly the entire $1 million.
Very few investors are aware of the fact that high cost stock funds can silently siphon away 75% of the investment gains over decades because most professionals in the investment industry have no interest in telling investors about the tyranny of compounding costs.
To the contrary, the investment management industry has a vested interest in keeping investors in the dark about fees, so bad investments like high cost stock funds can walk away with 75% of the market’s gains after decades of investing.
Fortunately, Uncle Alvin’s nieces and nephews who are reading this blog are no longer in the dark about fees and are now aware of the tyranny of compounding costs, so they can cut high cost stock funds out of their portfolios that leave investors with only 25% of the return.
Nieces and nephews can put much better investments into their portfolios, like low cost stock index funds with expense ratios under 0.05% that leave investors with nearly 100% of the return.
So Uncle Alvin says that one of the best things nieces and nephews can do to get started and stay on the road to great investment outcomes is:
1) follow Uncle Bogle’s expert investment advice to avoid investment management firms and high cost stock funds that leave investors with as little as 25% of the market’s return.
2) follow Uncle Warren’s expert investment advice to just buy low cost stock index funds that leave nieces and nephews with nearly 100% of the return.
BLOG POST 3 — Ask Uncle Alvin About His Unique Perspective on Real-Life Annual Costs of Management Fees and High Cost Funds
Let’s say a niece or nephew of any age is fortunate enough to receive a lump sum of $1 million, say by legal settlement or inheritance.
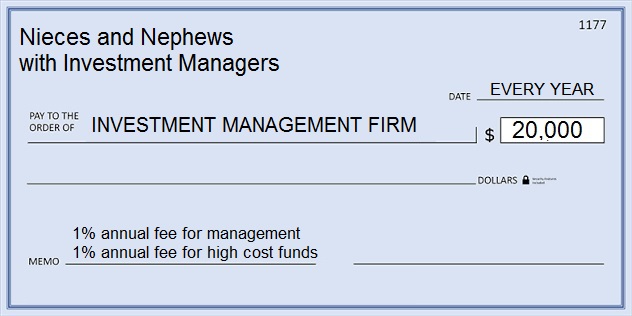
One option is they can place that $1 million with a traditional full-service investment, wealth or advisory management firm that charges an annual management fee of 1% and puts them in high cost funds that charge another 1% annual fee known as an expense ratio. In this case, the niece or nephew metaphorically “writes” a check for $20,000 to pay the total annual fees of 2% of assets the first year, and a check for 2% of the assets every year afterwards.
The insidious part of the investment management industry, unlike almost all other industries, is that the annual management fees and fund fees charged by investment, wealth and advisory management firms are never presented as recurring bills or invoices that nieces and nephews have to consciously take the time to write an actual check for or to make an online payment.
In this example of a $1 million account managed by investment management firms, the annual fees of $20,000 (or 2% of assets) are automatically and silently and invisibly deducted without any notice from the account — so nieces and nephews might not even be aware they are paying that much every year so they cannot make an informed and conscious decision about whether the costs are worth the services provided.
By going with full-service investment firms, nieces and nephews pay $20,000 or more in fees every year. Are the services received in a year worth $20,000? Over a lifetime, the tyranny of compounding costs can insidiously take away 75% of the total returns. Are the services received over a lifetime of investing worth giving up 75% of the return? The tyranny of costs means the benefits of full-service firms don’t seem to be worth the costs no matter how good the services might be.
A better option for Uncle Alvin’s nieces and nephews who know about Uncle Warren and Uncle Bogle’s unique perspectives is they can place that $1 million into Schwab or Vanguard or Fidelity. These are self-service brokerage firms that charge no management fees, and nieces and nephews can self-direct their investments by buying a low cost stock fund (such as the S&P 500 index fund offered by Schwab, stock symbol SWPPX) that charges a very low 0.02% annual expense ratio. In this case, the niece or nephew metaphorically “writes” a check for only $200 to pay the annual fee of 0.02% of assets the first year, and a check for 0.02% of the assets every year afterwards.
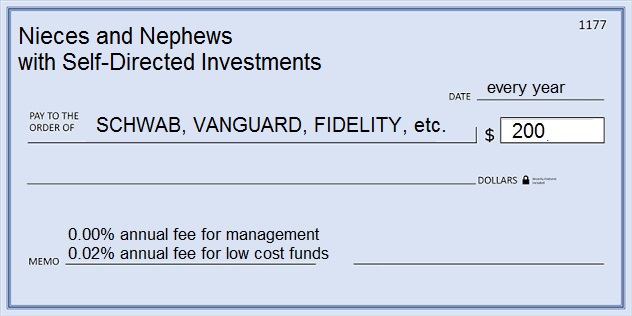
Uncle Alvin’s unique perspective on this $1 million lump sum example is that nieces and nephews are far better off following Uncle Warren and Uncle Bogle’s advice. By placing the money in self-directed investment accounts, nieces and nephews will have only $200 deducted every year for every $1 million invested, thereby avoiding the tyranny of compounding costs.
By choosing self-directed investment accounts, nieces and nephews can keep for themselves $20,000 for every $1 million invested, simply by not having to pay full-service fees. Consequently, by avoiding the tyranny of compounding costs, nieces and nephews keep nearly 100% of the returns over a lifetime of investing. This matters because nieces and nephews will then have that much more money to spend on the fun and important things in life — like family, charity, food, home, travel, and entertainment.
BLOG POST 4 — Ask Uncle Alvin About Uncle Fidelity’s Unique Perspective On Which Investors Did Best and — Forget About It
For most activities that nieces and nephews like to do, such as art or music or sports, the more you do, the better you do. For example, the more you practice painting and guitar and basketball, the better you do in those activities.
However for investing, the less you do, the better you do!
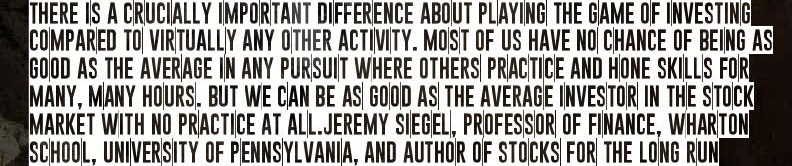
An example of this is a study that one of the largest fund companies in the world made — Fidelity Reviewed Which Investors Did Best And What They Found Was Hilarious — that showed Fidelity’s best-performing accounts were actually accounts where their customers bought Fidelity funds and then completely forgot about their accounts. In other words, the less that investors did, the better they did. In fact, when Fidelity’s investors forgot about it and did nothing more, they did the best.
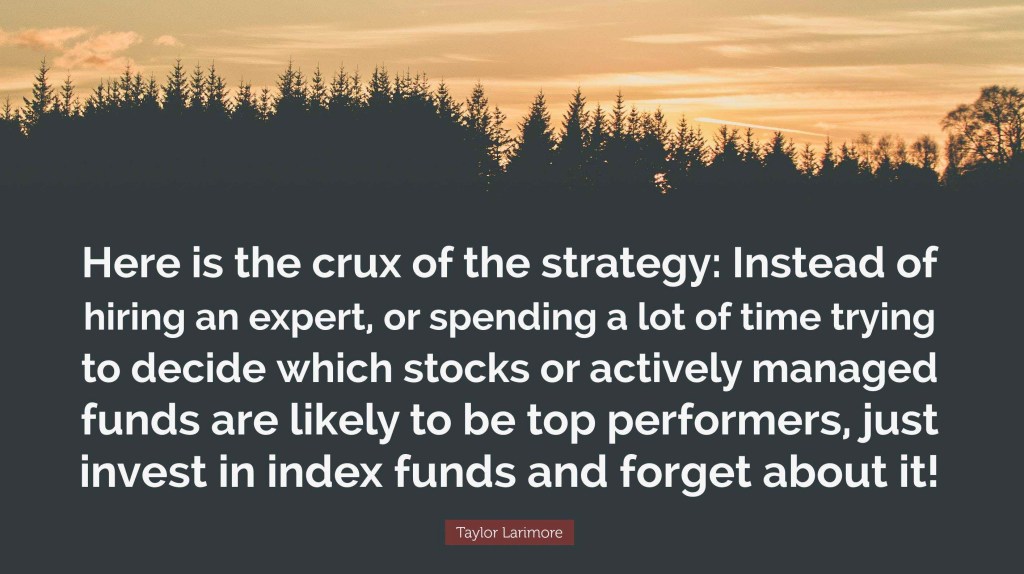
So if nieces and nephews ask what are the secrets to a meaningful life and successful investing, Uncle Alvin says three of the secrets are to:
1) work hard and have fun doing the things you like,
2) be helpful to others, and
3) get into the habit of putting part of birthday and holiday gifts and part-time and full-time jobs in an investment account at say Schwab and a retirement account at work, and regularly buy low cost stock index funds with expense ratios less than 0.05% like SWPPX —
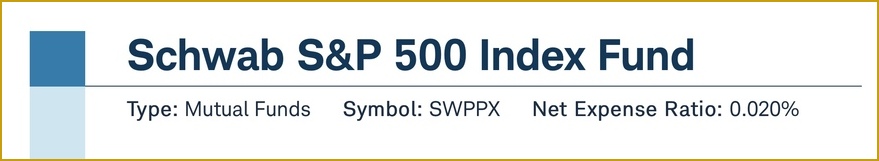
Then after buying low cost stock index funds, just … fuhgeddaboudit
BLOG POST 5 — Ask Uncle Alvin About Uncle Rip Van Winkle’s Unique Perspective On How Long To … Fuhgeddaboudit
Uncle Fidelity showed that investors who forgot about their investments, did the best. Of course, investors don’t want to completely … fuhgeddaboudit, because they want to eventually benefit from their investments. So nieces and nephews may ask Uncle Alvin, as a practical matter, how long should they … fuhgeddaboudit?
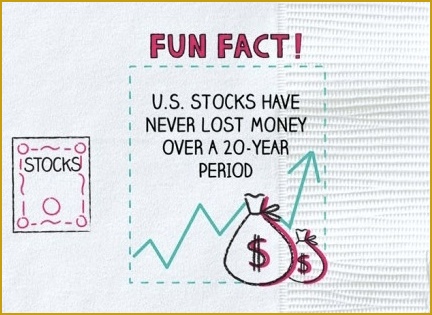
I now want to tell nieces and nephews about how Uncle Rip Van Winkle’s perspective on sleeping for 20 years applies to investing. As you can see from this article, What if Rip Van Winkle Invested in the U.S. Stock Market, there were many unexpected events and scary declines during every 20-year period for the U.S. stock markets, but investors who bought low cost stock index funds and did nothing else and just forgot about it for 20 years, always made money and did the best.
Stock markets are risky in the short-term, as investors saw in 2022 when the S&P 500 index fell into a bear market, but the risks recede and the rewards emerge in the long-term. In other words, investors who buy low cost stock index funds can experience significant risks and do poorly after 1 year or 3 years or 5 years or even 10 years.
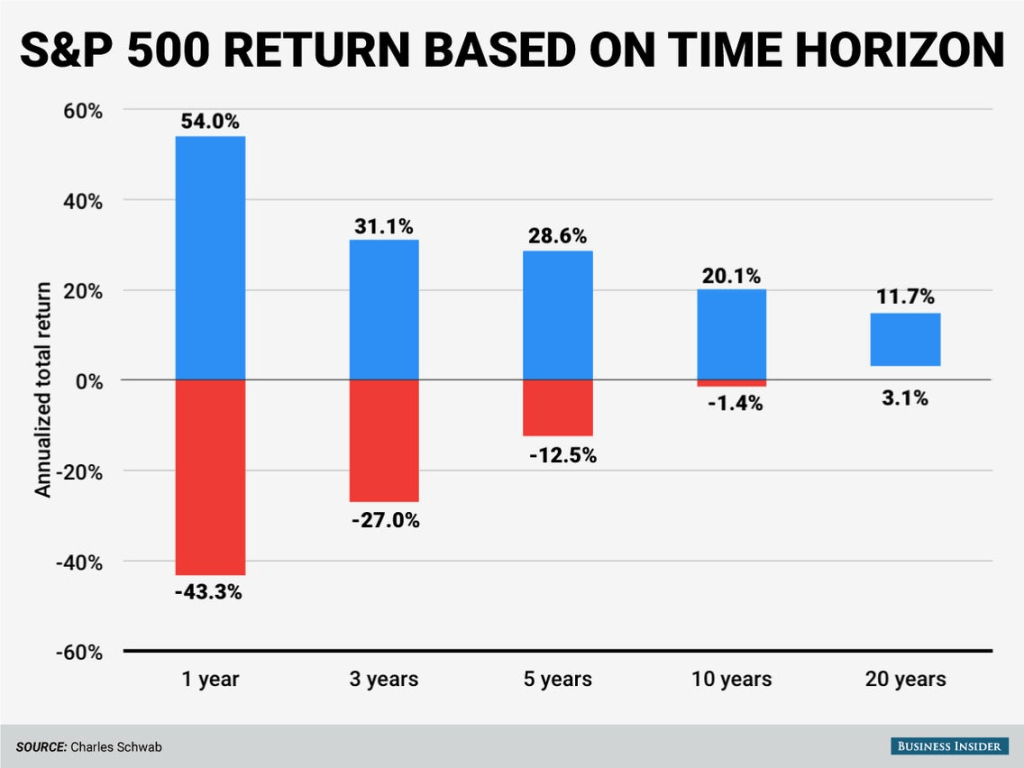
However, nieces and nephews who buy low cost stock index funds like Schwab’s S&P 500 index fund with an expense ratio under 0.05% (symbol SWPPX) and forget about it for 20+ years, can reap the rewards and make money in every 20-year period in history despite the unexpected surprises and scary markets that always happen along the way.
BLOG POST 6 — A Nephew Asks For Uncle Alvin’s Unique Perspective on Higher Risk Strategies to Maximize Returns
1) If the goal of investing is to build wealth, shouldn’t we be moving money to maximize the return?
2) How much of our net worth do you think we can allow to do high risk trades to maximize alpha?
For question 1), I agree the goal of investing is to build wealth. There is a popular perspective that buying a low cost stock index fund is “too slow” and “too boring” to build wealth, but my unique perspective is that nieces and nephews can build wealth faster than most investors by simply buying and holding a low cost S&P 500 index fund, because the S&P 500 builds wealth faster than 80% of all funds!

As for moving money to try to maximize the return, I would defer to Uncle Warren who says the best thing investors can do is to simply put their money in an S&P 500 index fund with an expense ratio less than 0.05%, meaning buy and don’t move money, or as Uncle Johnny Depp and Uncle Al Pacino would say, just buy and —
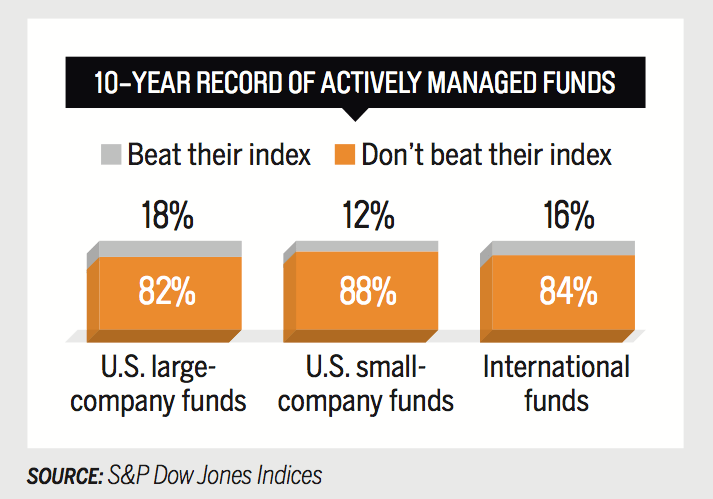
In theory, moving money may maximize return, but in practice, moving money is more likely to minimize return. For example, Uncle Bogle found that more than 80% of fund managers who actively move money around to try to beat an index like the S&P 500, don’t beat their index. Unfortunately, this means that more than 80% of investors who move money around to try to beat the market, don’t beat the market. In other words, for the vast majority of investors, moving money actually minimizes return.
For question 2), Uncle Warren recommends that investors put 90% of their money into an S&P 500 index fund and 10% into a bond fund. You seem to be a risk-tolerant nephew with an avid interest in learning more about investing, so my unique perspective is that instead of moving 10% of your money into a bond fund, you can consider modifying Uncle Warren’s recommended portfolio by moving 10% into higher risk assets and trading strategies to try to maximize alpha, because you can definitely learn more about investments by trying to maximize alpha with risk capital than being in a bond fund!
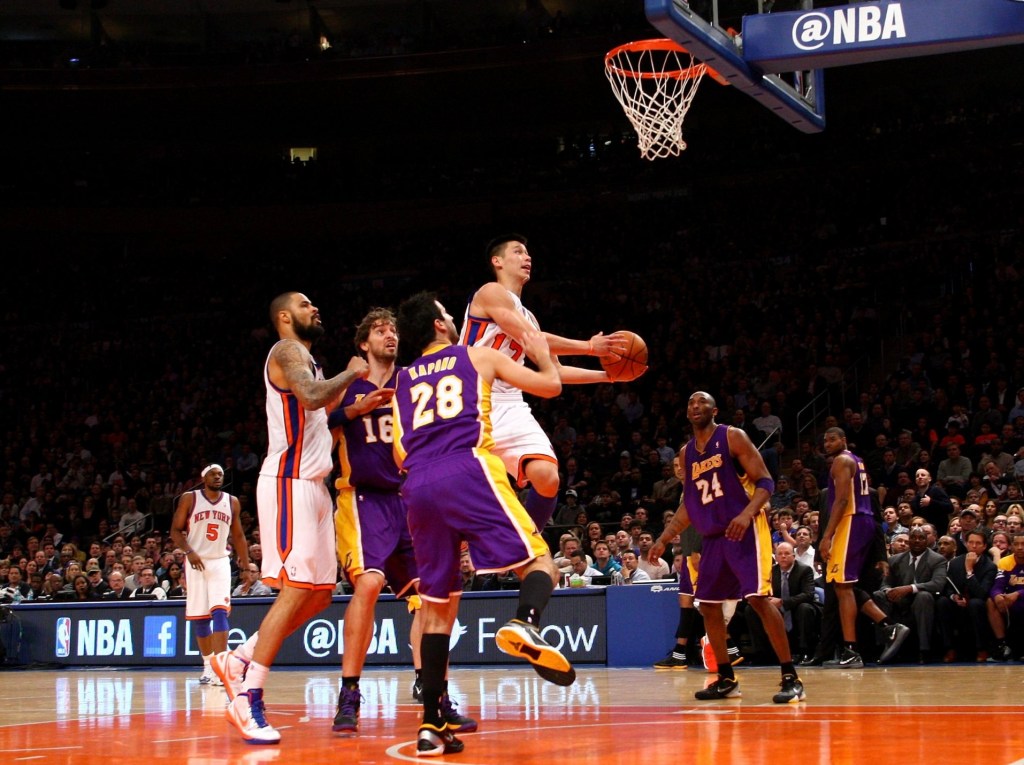
However, the number of people who can maximize alpha is probably like the number of people who can play in the NBA — a very small number. Everyone tries to generate alpha so it can be very tough to maximize alpha, but it might be very educational for you to consider the portfolio below that allows the use of risk capital to try to generate alpha with the dream of getting into the NBA one day, while limiting maximum losses to a small percentage of net worth and treating losses (inevitable along the way) as the cost of tuition in the learning process:
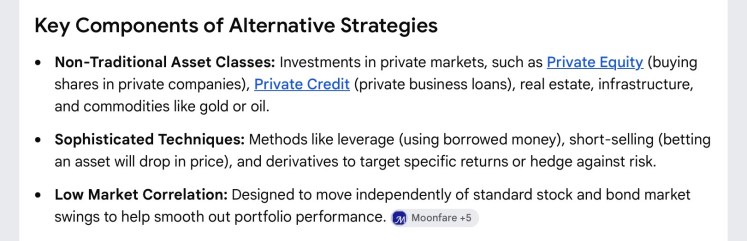
Uncle Warren’s Modified Portfolio For Risk-Tolerant Investors: 90% in low risk S&P 500 index funds and 10% in risk capital.
BLOG POST 7 — A Nephew Asks For Uncle Alvin’s Unique Perspective on Risk Capital and FOMO
I really appreciate your objective analysis and the opportunities/risks they offer for us. However, to borrow a term from the youths, using only 10% of net worth for risk capital gives me massive FOMO when I do accidentally hit NBA-level alpha gains. Ultimately, I realize that proper investor discipline is still the copacetic path.
Thanks for the kind comments! Uncle Alvin knows that nieces and nephews may find it fun and educational to try to hit NBA-level alpha gains and might have FOMO if they do not try to beat the S&P 500, because aunts and uncles including Uncle Alvin also enjoy trying to maximize alpha and learning more along the way.
My unique perspective on FOMO is that investing is not only objective and analytical — investing is also psychological. Rationally, investors should follow Uncle Warren’s objectively good advice and put their investments into very low cost S&P 500 index funds, with no FOMO.
Psychologically, risk-tolerant nieces and nephews who follow Uncle Warren’s advice but enjoy investing like Jeremy Lin enjoys basketball, might have big-time FOMO because they feel they don’t have enough in riskier assets and strategies to have a chance of getting into the NBA.
One unique and practical perspective that Uncle Alvin followed, and risk-tolerant nieces and nephews can also follow to minimize FOMO, is:
1) first, before doing anything else, max out the tax-deferred retirement accounts (401Ks, Roth and traditional IRAs, etc.) into low cost stock index funds with expense ratios less than 0.05%.
2) then allocate a portion of taxable investment accounts as risk capital for riskier assets and have fun working on a track record that can be good enough to get into the NBA!
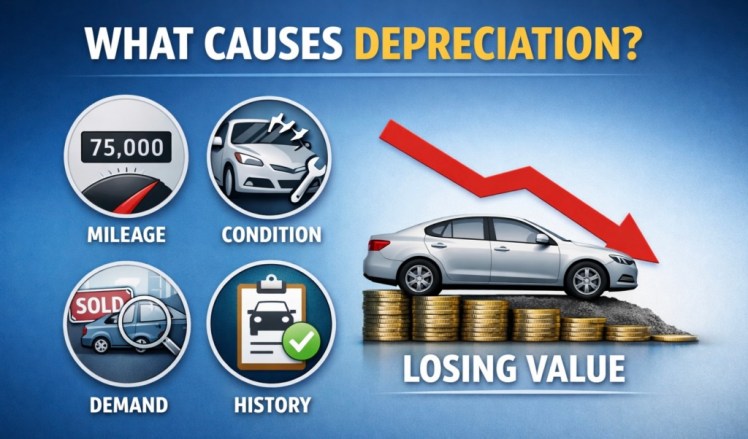
For example, once the tax-deferred accounts are maxed out, some nephews who are into cars may use most or even all of their discretionary income (also known as fun money) to buy and drive $50,000 cars that are likely to be worth only $15,000 in 10 years.
Other nephews who are not into cars but are into investments may use some or all of all their discretionary income to have fun investing $50,000 in riskier assets and alternative strategies that may be worth $150,000 (or $15,000) in 10 years.
BLOG POST 8 — A Nephew Asks For Uncle Alvin’s Unique Perspective on 401k Investment Options
Starting this month, we have access to the 401k plan through my employer, with some kind of employer match as well. We get to choose the investment that these funds go toward, so we wanted to get your perspective on which of these options might be good for us. The default is to go into the 2055 target date fund. I was thinking the S&P 500 Index fund might be a good option given its low expense ratio and good history. Let us know what you think – we are subscribing to the Uncle Alvin plan!
Great that you have access to the 401k plan in the new year! Very happy to provide my unique perspectives on investing based on personal experience and the wise perspectives of the greatest investors of all time like Uncle Warren and Uncle Bogle.
There are many investment options in your 401k plan to choose from. However, if you know about Uncle Warren’s perspective that the best thing investors can do is to put 90% of their money into a low cost S&P 500 index fund (see BLOG POST 1), and you know about Uncle Bogle’s perspective on the tyranny of compounding costs (see BLOG POST 2), then the best option out of all the investment options is the S&P 500 Index Fund that has an expense ratio of 0.05%.
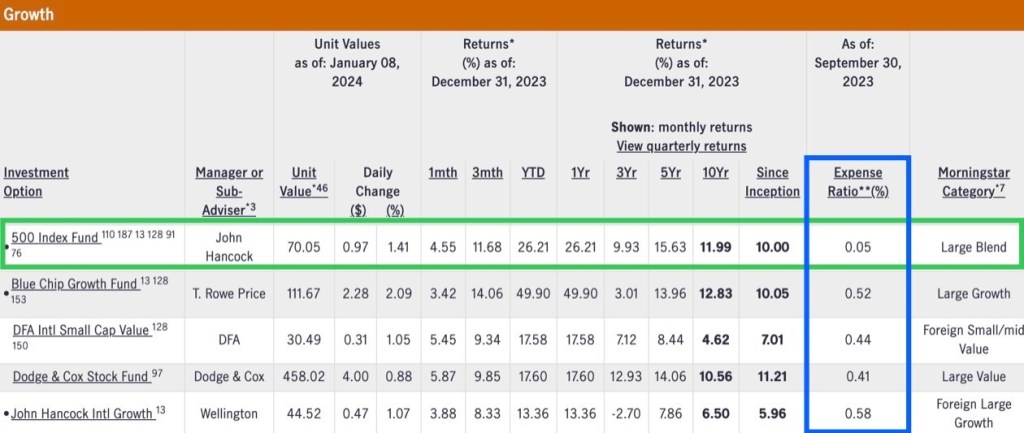
I looked at the other investment options and their expense ratios are generally around 0.5%, which means the other investment options are about 10 times more expensive than the S&P 500 index fund, and high expenses are bad for investment accounts. Regarding the default choice being target funds, Uncle Warren says investors are better off with 90% in S&P 500 index funds and don’t need more than 10% in bonds, but target funds typically increase over time to 60% in bonds, which means investors in target funds unfortunately can have 6 times more in bonds than Uncle Warren recommends.
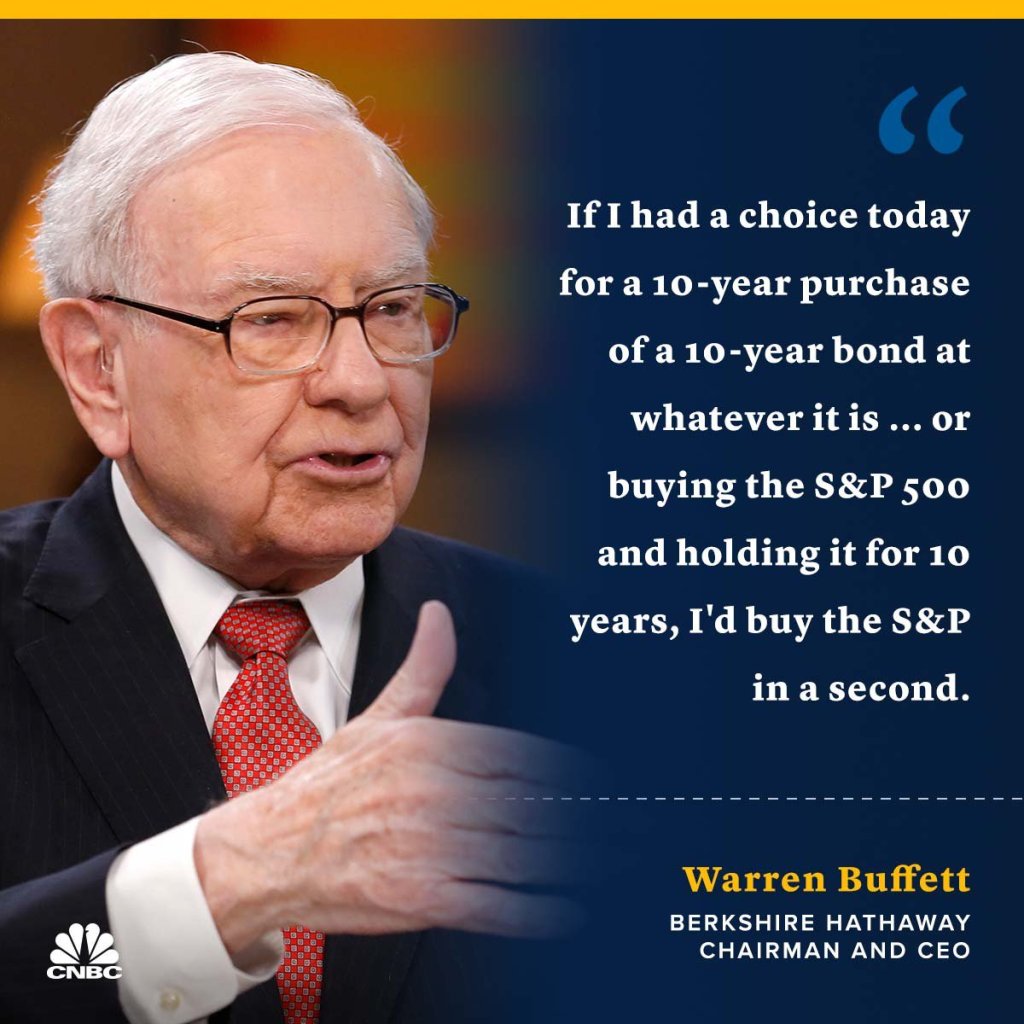
Fortunately, your 401k offers a low cost S&P 500 index fund, and Uncle Alvin agrees with Uncle Warren that S&P 500 index funds are the best 401k investment option for nieces and nephews of all ages. Always fun to answer any questions about my favorite subject any time. Happy to provide my perspective and you can ask others for their perspectives, and then use your good judgment to decide what is best for your fam!
BLOG POST 9 — Ask Uncle Alvin About Unique Real Estate and Stock Market Facts Overlooked By Investors
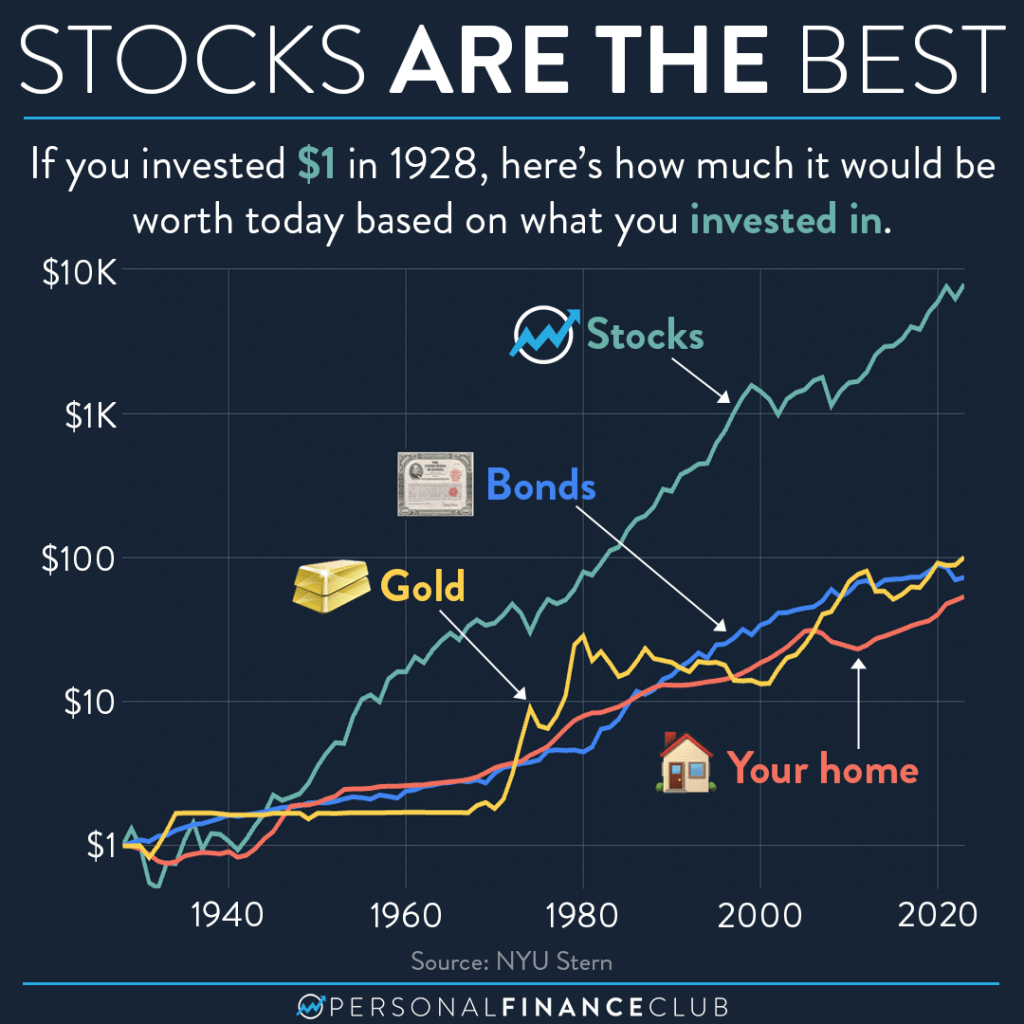
My kids have been asking and I do tell them to invest in index funds and to just leave it. For now, they each have homes of their own and the next step is to invest in the stock market. Real estate has increased a lot even with interest rates going up — is it better to invest more in real estate or stocks?
Your kids are doing great starting out as homeowners and now looking to invest in the stock market! Uncle Alvin wants to provide them and fellow nieces and nephews with unique real estate and stock market facts that may be helpful but are little-known and overlooked by most investors.
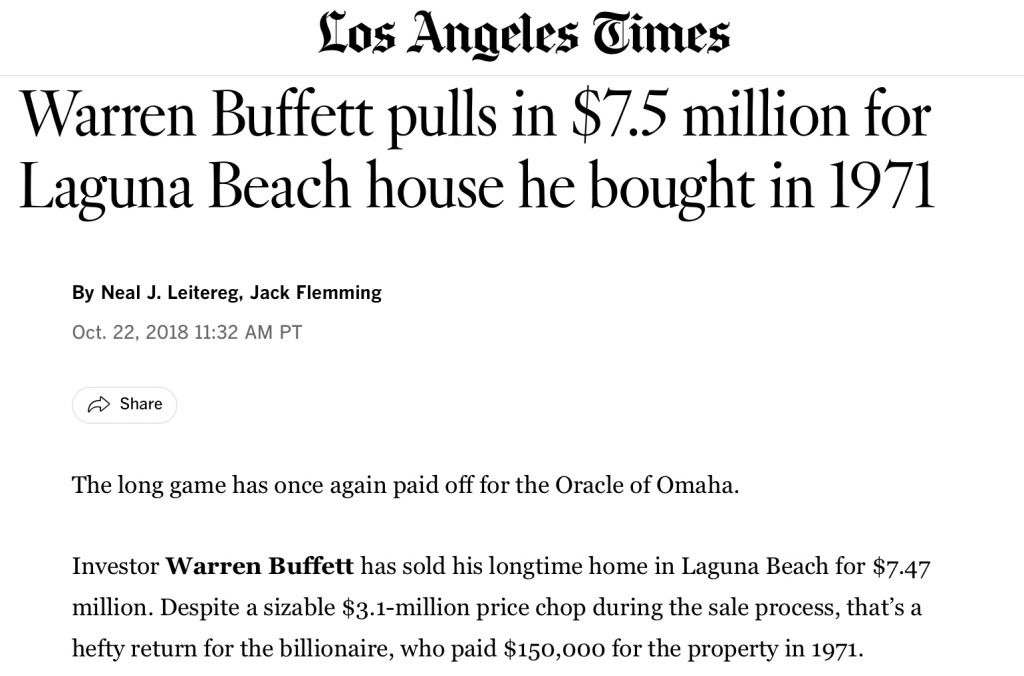
The first real estate fact is that Uncle Warren Buffett bought a Laguna Beach home in 1971 for $150,000 and sold the home 47 years later in 2018 for $7.5 million.
The second stock market fact is that an investor who bought an S&P 500 fund in 1971 with $150,000 could sell the fund 47 years later for $16.5 million.
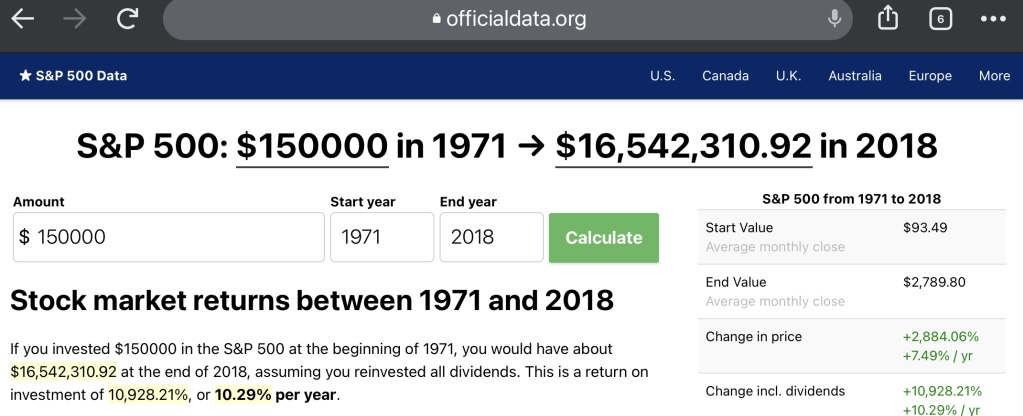
These two facts overlooked by most investors show that a stock market investment in an ordinary index fund that any investor can buy, beats a real estate investment in one of the best locations in the world that very few investors can buy.
A key real estate fact overlooked by many investors is that only prime locations increase in value like Uncle Warren’s Laguna Beach home that appreciated after 47 years from $150,000 to $7.5 million. Most real estate properties are in non-prime locations that typically appreciate only slightly faster than inflation.
This means that $150,000 invested in real estate in most locations in 1971 that appreciated slightly faster than inflation would increase 47 years later to $1 million, less than Uncle Warren’s Laguna Beach home that increased to $7.5 million and much less than the S&P 500 index fund that increased to $16.5 million.
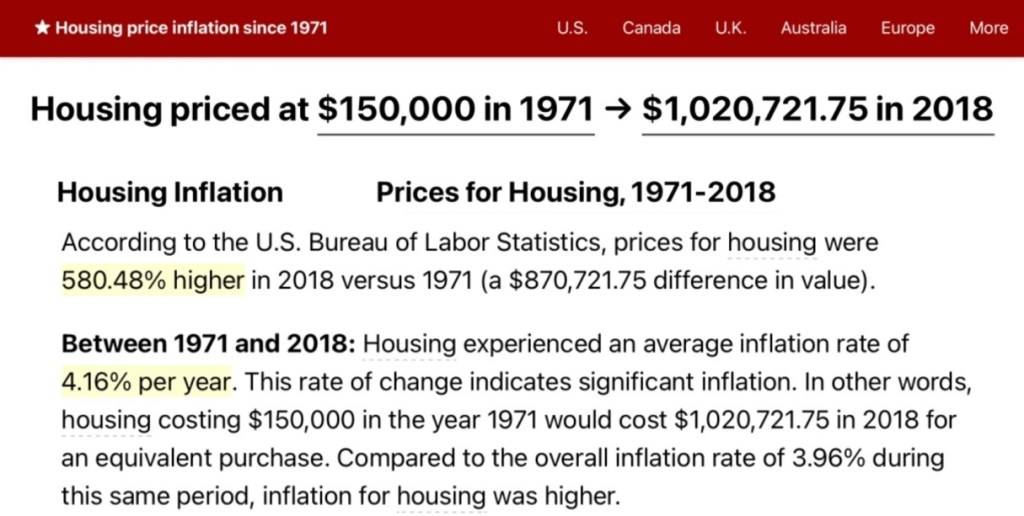
Unfortunately, very few people can afford to buy real estate in prime locations. Fortunately, anyone can buy S&P 500 index funds with expense ratios less than 0.05% and generate superior long-term returns from the stock market that significantly beat the long-term returns from real estate in nearly all locations, even prime locations like Uncle Warren’s Laguna Beach home.
Another real estate fact overlooked by investors is that real estate has high expenses in the form of property taxes, insurance, utilities, maintenance and repairs — and unfortunately the tyranny of compounding costs (see BLOG POST 2) makes real estate equivalent to high cost mutual funds that take away roughly 75% of the return over the long term and leave investors with only 25% of the return.
This means if $150,000 is invested in real estate that returns $1 million after 47 years, the tyranny of compounding costs takes away roughly $750,000 of the return and leaves the real estate investor with only $250,000 of the gain. In contrast, if $150,000 is invested in an S&P 500 index fund that returns $16 million after 47 years, the low cost index fund takes away very little of the return and leaves the stock market investor with nearly $16 million.
Finally, perhaps the most important fact overlooked by many homeowners is that the increase in the value of their home cannot be used as a future income stream because the only way to do that would be to use a home equity loan or line of credit, which is the worst possible thing a homeowner can do. In fact, a personal residence is not a financial investment because a home does not provide spendable income from price appreciation.
Instead, the purpose of home ownership is not purely financial but is primarily psychological — a home should provide good family memories over the years and peace of mind when the mortgage is paid off. In comparison, the purpose of a low cost S&P 500 index fund is purely financial — the S&P 500 should increase in value faster than inflation and home prices to provide ample spendable income in 20+ years.
It’s great the kids bought their first home sweet home and are next planning to invest in the stock market. My unique perspective is that home ownership and stock investing are both very important things for nieces and nephews to do — buy a home as a nice place to live comfortably and then follow Uncle Warren’s expert advice to buy low cost stock index funds like SWPPX that has an expense ratio under 0.05% and forget about it for 20+ years.
At that point 20+ years from now, having a paid off home with a lifetime of precious memories and having low cost stock index funds that provide a good income stream would be a great situation for nieces and nephews to be in!